The Magnetic Stripe Is Obsolete. So Why Are We Still Using It?
An Opinion by Vincent Torres
Founder & CEO, Metal-CreditCard.com
October 2026
It’s Time to Retire the Weakest Link in Our Payment Cards
I’ve spent more than a decade working with credit cards, debit cards, and the technology behind them. As the founder of Metal-CreditCard.com, I’ve watched the payment industry evolve from magnetic stripes to EMV chips, contactless payments, and now digital wallets.
And after all these years, I keep coming back to one simple question.
Why the hell are we still putting magnetic stripes on credit cards?
Seriously.
We have microchips capable of generating unique security codes for individual transactions. We have contactless payment technology that allows consumers to tap a card or smartphone. We have biometric authentication, digital wallets, tokenization, and an entire financial industry investing billions in fraud prevention.
Yet we continue putting a strip of magnetic material on the back of our cards that contains static payment data and can be copied by criminals using equipment that has existed for decades.
At what point do we admit that the magnetic stripe has become more of a liability than an asset?
And before anyone points out that my own company still manufactures metal cards with magnetic stripes, don’t worry. We’re going to talk about that, too.
Because I’m not going to pretend this conversation doesn’t affect my own business.
A Great Invention That Should Have Retired Years Ago
Let’s give credit where credit is due.
The magnetic stripe was a revolutionary piece of technology.
Developed by IBM in the early 1960s and standardized for payment cards in 1969, it helped transform the financial industry. Before magnetic stripes, credit card transactions often required merchants to manually imprint card information onto carbon paper.
Imagine standing at a checkout counter today waiting for a cashier to make a physical copy of your credit card.
That’s essentially where we were.
The magnetic stripe made electronic payment processing faster, easier, and more practical for businesses around the world.
But here’s the problem.
Just because something revolutionized an industry 60 years ago doesn’t mean it belongs in that industry forever.
Technology evolves. Security threats evolve. Criminals evolve.
And at some point, we need to stop protecting outdated technology simply because we’ve become comfortable with it.
The Magnetic Stripe Has Become the Problem Child
We’ve all seen the stories.
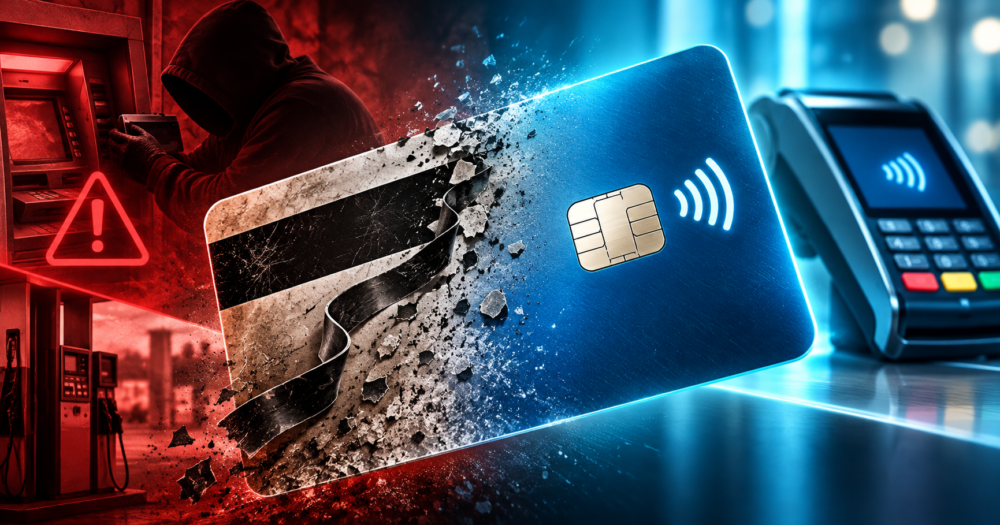
Someone puts a skimmer on an ATM.
Someone installs a skimming device inside a gas station pump.
A compromised payment terminal at a convenience store captures card information.
Suddenly, people are finding unauthorized transactions on accounts they thought were secure.
And here we go again.
Magnetic stripe skimming isn’t some sophisticated futuristic hacking technique. It’s an old vulnerability that criminals continue exploiting because the technology remains in circulation.
Here’s what makes it particularly frustrating.
Unlike modern EMV chip transactions, which generate unique cryptographic information for each payment, traditional magnetic stripes rely on static information.
That information can be copied.
And when criminals capture the necessary data, they may be able to create counterfeit magnetic stripe cards or attempt fraudulent transactions wherever vulnerable payment systems still accept them.
Now, I’m not suggesting that removing magnetic stripes will eliminate credit card fraud. That would be ridiculous.
Online fraud, stolen credentials, account takeovers, and compromised merchants aren’t going anywhere just because we stop swiping cards.
But why continue supporting a technology with a well-documented weakness when better alternatives already exist?
We don’t need to eliminate every possible threat to justify eliminating one we already understand.
At some point, enough is enough.
We Already Have the Replacement
Look at the payment cards in your wallet.
Chances are, most of them have an EMV chip. Many also support contactless payments.
For those unfamiliar with the terminology, EMV refers to the secure chip technology used in modern payment cards. NFC, or Near Field Communication, is the short-range wireless technology commonly used for contactless payments.
These technologies aren’t identical, but both can support secure EMV transactions.
The important distinction is that modern EMV transactions use dynamic security information rather than relying solely on the static data stored on a magnetic stripe.
That’s a significant improvement.
And here’s something people seem to forget.
We don’t even need contactless payments to eliminate the magnetic stripe.
A conventional EMV chip card can still be inserted into a payment terminal.
If tapping doesn’t work, insert the chip.
If the chip reader malfunctions, the merchant can troubleshoot the terminal or provide another payment option.
Why should our default solution be to fall back on decades-old technology that introduces an additional opportunity for fraud?
I understand the argument for redundancy. As someone who works with physical payment cards, I appreciate backup systems.
But redundancy should improve reliability without unnecessarily compromising security.
Otherwise, what the hell are we really accomplishing?
PCI Should Help Lead the Conversation
Let’s talk about PCI.
The Payment Card Industry Security Standards Council helps establish the security standards businesses follow when handling payment card information.
PCI DSS is an important part of protecting consumers and the businesses that accept their payments.
But there’s an important distinction.
PCI does not independently dictate that every credit or debit card must have a magnetic stripe. Individual payment networks, including Visa and Mastercard, establish their own card issuance and transaction acceptance rules.
Nevertheless, I believe PCI and the major payment networks should be working together to accelerate the elimination of magnetic stripe dependence.
Think about the irony.
The payment industry invests enormous resources protecting cardholder information, developing secure processing systems, establishing compliance requirements, and combating fraud.
Yet we continue supporting an old payment method whose inherent limitations are well understood.
Wouldn’t eliminating unnecessary magnetic stripe transactions simplify at least part of that security challenge?
We should be asking why magnetic stripe acceptance continues where secure alternatives are already available.
I’m not advocating that banks abandon consumers who depend on older payment infrastructure.
I’m advocating that the industry stop treating outdated infrastructure as a permanent excuse for maintaining outdated technology.
At some point, the backup system becomes the vulnerability.
China Is Already Showing Us What the Future Looks Like
Now, here’s where things get interesting.
Look at China.
While American consumers were transitioning from magnetic stripes to EMV chips, China experienced a different payment revolution.
Mobile wallets, particularly Alipay and WeChat Pay, transformed how millions of people conduct everyday transactions.
And contrary to what some might assume, this transition was not primarily driven by NFC.
It was driven by QR codes.
Consumers open an app, scan a code, authorize the payment, and move on.
No magnetic stripe.
No physical card exchange.
Often, no traditional card terminal.
According to the World Bank’s Global Findex data, approximately 81.1% of Chinese adults owned a debit card in 2024.
That’s an interesting statistic because it challenges the assumption that mobile payment adoption necessarily eliminates debit card ownership.
Consumers can maintain traditional banking relationships while increasingly conducting transactions through their phones.
And that’s precisely the point.
The future of payments isn’t necessarily about eliminating credit cards or debit cards. It’s about eliminating the need for outdated methods of using them.
China has demonstrated that an enormous population can adopt digital payment technology without relying on magnetic stripe transactions at the checkout counter.
Certainly, China’s financial system, regulatory environment, and consumer behavior are different from those in the United States.
But the lesson remains relevant.
When businesses and consumers have practical alternatives, payment habits can change dramatically.
Mastercard Has Already Started the Countdown
Here’s something that should tell us where this industry is going.
Mastercard has already announced its plan to retire magnetic stripes.
Starting in 2024, magnetic stripes were no longer required on newly issued Mastercard cards in many markets.
Beginning in 2027, U.S. banks will no longer be required by Mastercard to issue chip cards with magnetic stripes.
By 2029, Mastercard plans to stop issuing new credit and debit cards with magnetic stripes, subject to certain exceptions.
And by 2033, its broader phaseout is expected to be complete.
I applaud Mastercard for taking that initiative.
But I have another question.
Why should consumers have to wait until 2033?
That’s another seven years from where we stand today.
Seven years of maintaining compatibility with technology that most modern consumers rarely need.
I understand that payment networks operate globally. Some regions still depend on older terminals, and upgrading infrastructure requires money, planning, and coordination.
Those are legitimate concerns.
But we should distinguish between a reasonable transition period and unnecessary delay.
If the technology is already available, the security advantages are established, and consumers are increasingly comfortable using it, why not accelerate the transition wherever practical?
And What About Cryptocurrency?
We’re also living through an interesting period in the evolution of money itself.
Cryptocurrencies, stable coins, digital wallets, and new payment infrastructure are challenging traditional assumptions about how money should move.
I’m not suggesting Bitcoin will replace Visa or Mastercard tomorrow.
Nor do I believe cryptocurrency automatically offers better consumer protection than conventional banking.
But the emergence of these alternatives raises an important question.
Why are we designing payment systems for the future while continuing to preserve technologies from the past?
Whether a consumer pays with a traditional bank account, a credit card, a smartphone, or some future digital currency, the direction is becoming increasingly clear.
Payments are becoming more digital, more connected, and less dependent on the physical exchange of financial information.
The magnetic stripe simply doesn’t fit naturally into that future.
Now, Let’s Address the Elephant in the Room: Metal-CreditCard.com
Here’s where this conversation gets personal.
If you’ve followed Metal-CreditCard.com over the years, you’ve probably heard me make something very clear.
MCC will not compromise the integrity of a fully metal credit card just to accommodate contactless technology.
I’ve said it before, and I’m saying it again.
That has been one of the defining principles behind our business.
We manufacture fully metal payment cards. Not plastic cards disguised as metal. Not hybrid cards built around plastic sections to accommodate wireless signals.
Real metal cards.
Our process preserves the functionality of the customer’s original EMV chip and provides magnetic stripe functionality where supported.
Our cards do not offer conventional NFC contactless payments.
And you know what?
I’m okay with that.
Because when I started MCC, I wasn’t trying to manufacture every conceivable type of payment card.
I wanted to create something distinctive. Something with substance. Something that felt different from the plastic cards banks have been issuing for decades.
A fully metal card was the product.
That was the point.
And it still is.
But here’s where some people might accuse me of contradicting myself.
How can I advocate for contactless payment technology while running a company that has publicly resisted incorporating it into our products?
It’s a fair question.
And my answer is pretty damn simple.
Recognizing the future doesn’t mean I have to abandon what I believe in today.
No, MCC Isn’t Going Hybrid. And That’s Okay.
There’s an evolution happening within the custom metal credit card industry.
Hybrid cards, which combine metal and other materials to accommodate wireless payment technology, are one approach to addressing the limitations of conventional fully metal cards.
Companies such as FluidPrintWorks.com are positioned to pursue that evolution.
And I support that.
In fact, I want them to succeed.
They can spearhead the development and adoption of hybrid custom metal payment cards.
They can take that technology forward, develop their products, and help establish what the next generation of custom payment cards might look like.
But does that mean I’m going to bend the knee and start manufacturing hybrid cards at MCC?
Hell no.
Not because I think hybrid cards are bad products.
Not because I don’t believe NFC is the future.
And certainly not because I’m afraid of competition.
It’s because I know exactly what I want MCC to be.
We’ve built our identity around fully metal cards, and I’m not interested in watering that down simply to chase every technological trend that comes along.
There’s room in this industry for different approaches.
Fluid Print Works can focus on advancing hybrid card technology.
MCC can continue doing what it does best.
And consumers can decide which product better suits their needs.
Competition and technological advancement don’t require every company to manufacture the same damn thing.
Yes, I Know This Could Eventually Put MCC Out of Business
Now let’s take this conversation one step further.
What happens when magnetic stripes are completely eliminated?
What happens when contactless technology becomes so widespread that conventional fully metal cards are no longer practical for most consumers?
What happens when the industry eventually moves beyond physical payment cards altogether?
The answer isn’t complicated.
MCC, at least as we know it today, could eventually become a thing of the past.
And I’m completely okay with that.
Let me explain.
I founded Metal-CreditCard.com in 2013.
I’ve spent years building this business, developing our manufacturing processes, serving customers, and creating a product that I genuinely believe in.
I’m proud of what we’ve accomplished.
But I’m also realistic.
No product lasts forever.
No business model is guaranteed permanent relevance.
And technological progress doesn’t give a damn how emotionally attached a business owner might be to something he’s created.
Think about the companies that manufactured typewriters, cassette tapes, photographic film, and countless other products that were once considered essential.
Some adapted. Some found smaller specialty markets. Others disappeared.
That’s business.
That’s technology.
That’s progress.
And I’m not going to stand here advocating for better payment security while secretly hoping the financial industry keeps magnetic stripes alive just so my company can continue manufacturing them.
That would make me a hypocrite.
If the eventual retirement of magnetic stripes contributes to a safer payment environment, then I’m willing to accept whatever consequences that brings to MCC.
Does that mean we’re closing tomorrow?
Of course not.
Does that mean we’re abandoning fully metal cards?
Absolutely not.
It means we’re going to continue manufacturing the product we’ve built our reputation around for as long as there’s a viable market for it.
We’ll continue producing fully metal cards with functional EMV chips and magnetic stripes while the issuing banks and payment networks continue supporting that technology.
And we’ll continue giving our customers the distinctive product they’ve come to expect.
But when the day eventually arrives that our product no longer makes practical sense, I’m not going to pretend the world owes MCC another decade of relevance.
I’d rather see the payment industry move forward than watch it remain vulnerable just to protect my own business model.
There’s a Difference Between Standing by Your Principles and Standing in the Way of Progress
I think this is where some business owners get themselves into trouble.
They confuse loyalty to their products with resistance to change.
They become so invested in what they’ve created that they stop acknowledging what’s happening around them.
I don’t want to be that guy.
I can believe that fully metal payment cards offer a unique product experience while simultaneously recognizing that NFC, digital wallets, and other payment technologies represent the future.
Those positions aren’t mutually exclusive.
One is a decision about the product I choose to manufacture.
The other is an acknowledgment of where the broader financial industry is heading.
And if that future eventually makes my product obsolete, so be it.
That doesn’t erase the years of work that went into building MCC.
It doesn’t invalidate the customers who have enjoyed our cards.
And it certainly doesn’t mean the business was a mistake.
It means we created something people wanted during a particular chapter of payment technology.
There’s nothing wrong with that.
Not every successful business has to last forever to have been worth building.
Enough Is Enough
My position is simple.
The magnetic stripe served its purpose.
It helped create the modern electronic payment industry. It made transactions faster, helped businesses operate more efficiently, and contributed to the global financial infrastructure we rely on today.
But we have moved beyond the limitations that made it necessary.
We have EMV chips.
We have contactless cards.
We have smartphones and digital wallets.
We have alternative payment systems that didn’t even exist when magnetic stripes became standard.
And we have decades of evidence demonstrating how vulnerable static magnetic stripe data can be.
So what exactly are we waiting for?
I believe the payment networks, financial institutions, terminal manufacturers, and security standards organizations should accelerate the transition toward a world where magnetic stripes are no longer required for everyday payments.
Not recklessly. Not overnight. And not at the expense of consumers who genuinely need accessible, reliable payment methods.
But deliberately, aggressively, and with a clear objective.
As for Metal-CreditCard.com?
We’re not changing our identity to chase NFC.
We’re not suddenly switching to hybrid cards because the industry is moving in that direction.
We’re going to keep manufacturing fully metal cards with functional chips and magnetic stripes while that technology remains supported and commercially viable.
And if the day comes when the very technology that helped build MCC becomes obsolete, I’ll accept that.
Because I didn’t build this company to hold the entire payment industry hostage to my business model.
I built it because I believed in a product.
I still do.
But believing in your product doesn’t mean you should stand in the way of progress.
The magnetic stripe was a remarkable invention.
It’s time to thank it for its service.
And retire it.
And if MCC eventually retires alongside it?
Well, we’ve had one hell of a ride.
Vincent Torres
Founder & CEO
Metal-CreditCard.com